The Difference Between Being Cheap and Being Financially Wise Being financially wise isn't about spending the least amount of money possible. It's about making decisions that give your money the greatest possible value. Have you ever bought something because it was cheap, only to replace it a few months later? Or avoided paying for a …
The Difference Between Being Cheap and Being Financially Wise
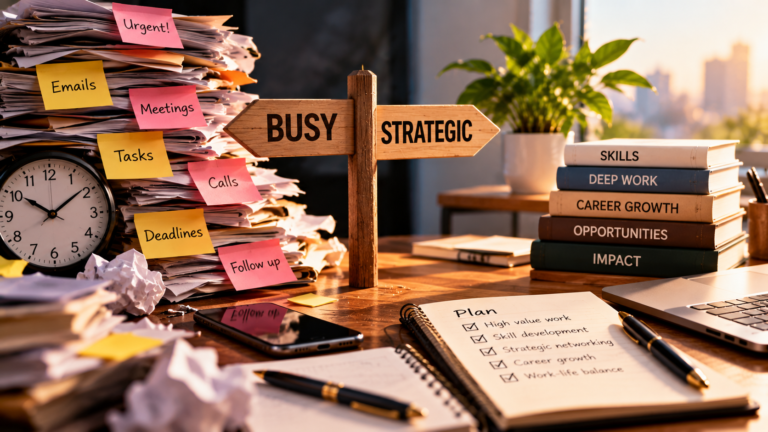
Being financially wise isn’t about spending the least amount of money possible. It’s about making decisions that give your money the greatest possible value.
Have you ever bought something because it was cheap, only to replace it a few months later? Or avoided paying for a service that could have saved you hours of work, only to spend that time struggling with the task yourself?
Sometimes, trying to save money can actually cost you more.
This is where the difference between being cheap and being financially wise becomes important.
One focuses primarily on spending less. The other considers value, quality, time, priorities, and long-term consequences.
1. Cheapness Focuses on Price; Financial Wisdom Focuses on Value
Imagine you need a pair of shoes.
You find one pair for $15 and another for $45. The cheaper pair looks attractive because it costs less upfront.
However, suppose the cheaper pair wears out after two months, while the more expensive pair lasts two years with reasonable care.
The cheaper option may not be the better financial decision.
Of course, a higher price doesn’t automatically mean better quality. The point is to evaluate what you’re getting for your money instead of assuming the lowest price is always the best choice.
Being financially wise means asking, “What value will this purchase give me over time?”
2. Being Cheap Can Make You Pay Twice
One common mistake is buying the cheapest available option without considering durability, reliability, or suitability.
This can happen with clothing, electronics, household equipment, business tools, and everyday essentials.
You buy something that doesn’t meet your needs. You replace it. You spend more money correcting the original decision.
That doesn’t mean you should always choose premium products. Sometimes an affordable option works perfectly well.
The smarter approach is to compare quality, expected lifespan, maintenance costs, and your actual needs before deciding.
3. Financial Wisdom Understands the Value of Time
Money matters, but time matters too.
Suppose you spend three hours trying to complete a task that a reasonably priced professional could handle in one hour. Depending on your circumstances, paying for help might be worthwhile.
Alternatively, if you have the time and enjoy learning the skill, doing it yourself may be the better choice.
Neither option is automatically right.
Being financially wise means considering the complete cost of a decision, including the time, effort, stress, and money involved.
The cheapest option on a receipt isn’t always the cheapest option overall.
4. Being Cheap Can Mean Neglecting Important Needs
There is a difference between avoiding waste and refusing to spend money on things that genuinely matter.
Delaying necessary repairs can allow small problems to become expensive ones. Avoiding appropriate healthcare because of the immediate cost can create greater difficulties later. Refusing to invest in essential work equipment may limit your ability to earn.
Financial wisdom doesn’t mean spending without limits. It means recognizing which expenses protect your well-being, responsibilities, and future opportunities.
Sometimes, spending money today is the decision that prevents a bigger expense tomorrow.
5. Financially Wise People Know When to Spend and When to Save
A financially wise person doesn’t automatically reject every expensive purchase or approve every cheap one.
Instead, they evaluate the decision.
Before spending, ask yourself:
- Does this meet a genuine need or meaningful desire?
- Can I afford it without neglecting essential expenses?
- Is there a more affordable option that offers similar value?
- How long will it last?
- Will I use it regularly?
- What financial goal might this purchase delay?
These questions encourage intentional spending rather than spending based purely on price, emotion, or appearances.
6. Discounts Don’t Automatically Mean Savings
A product marked down from $100 to $60 may look like a bargain.
But if you didn’t need the product and wouldn’t have bought it without the discount, you haven’t necessarily saved $40. You’ve spent $60.
Retail promotions can create a sense of urgency that encourages people to buy things they don’t need.
A financially wise shopper evaluates the purchase itself, not just the discount.
The question isn’t simply, “How much am I saving?”
It’s also, “Would I choose this purchase at its current price if there were no promotion?”
7. Financial Wisdom Includes Planning Ahead
People often end up spending more because they make decisions at the last minute.
They pay extra for urgent delivery, replace items they could have maintained, or purchase necessities without comparing options.
Planning ahead gives you time to research, compare prices, save gradually, and avoid unnecessary pressure.
You don’t have to plan every detail of your life. Even a basic shopping list, maintenance schedule, or monthly spending plan can improve your decisions.
8. Stop Trying to Look Financially Successful
Another important part of financial wisdom is understanding that spending isn’t proof of wealth.
Buying expensive things to impress people can leave you with less money for savings, investments, debt repayment, or future goals.
You don’t have to buy the newest phone, wear a particular brand, or maintain an expensive lifestyle to demonstrate success.
A better measure of financial progress is whether your money supports the life you genuinely want.
The Goal Is Not to Spend the Least
Being cheap and being financially wise may sometimes lead to the same decision. Both might choose an affordable product or decide against an unnecessary purchase.
The difference is the reasoning behind the decision.
Cheapness asks, “How can I spend less?”
Financial wisdom asks, “What is the best decision for my circumstances, priorities, and future?”
That second question allows room for saving, investing, enjoying your money, paying for quality, and spending on experiences that matter.
You don’t have to spend more to live better, and you don’t have to spend less at every opportunity to be financially responsible.
You simply need to understand what your money is doing for you.